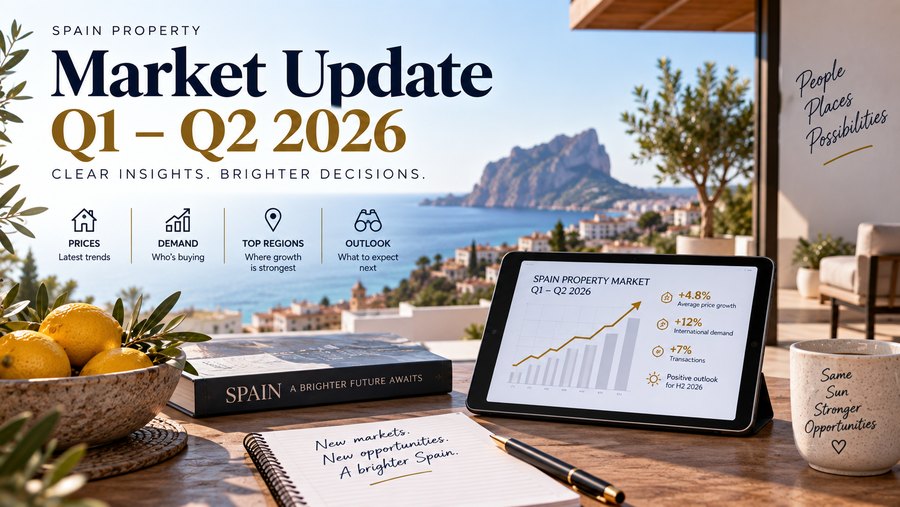
Spain’s property market entered 2026 with a combination that continues to support residential demand: economic growth, easing inflation, a lower interest-rate environment than at the recent peak, strong international interest and a persistent shortage of homes in many of the places buyers most want to live.
The result through Q1 and Q2 has been a market that remains remarkably resilient. This is not simply a story about holiday homes on the coast. Spain is attracting domestic buyers, international families, retirees, remote workers and investors, while prime destinations such as the Costa del Sol continue to operate within their own particularly competitive supply-and-demand dynamics.
Spain’s Economic Backdrop Remains Supportive
The wider economy matters because property rarely moves in isolation. The update highlights Spain’s comparatively strong GDP performance, with growth running ahead of several major European economies. Inflation has also moderated from the extremes seen after the pandemic and energy shock, helping restore a degree of confidence to household and investor decision-making.
Employment is another important part of the picture. Spain still has a higher unemployment rate than many northern European countries, but the long-term direction has improved significantly from the levels seen following the financial crisis. That matters for the domestic housing market because stronger employment and economic activity underpin demand beyond the international buyer segment.
Interest rates have also become less restrictive. After the sharp tightening cycle that affected affordability across Europe, the direction of Euribor and European rates has been more favourable for borrowers. Lower financing costs do not suddenly make property cheap, but they can bring previously hesitant buyers back into the market and improve affordability at the margin.
Demand Is Still Running Ahead of Supply
Perhaps the most important structural theme is the imbalance between the number of homes required and the number being delivered. The video illustrates a substantial gap between housing demand and new supply. Whatever short-term movements occur in mortgage rates or buyer confidence, limited stock places continuing pressure on desirable areas.
This is particularly visible in established coastal markets. Good-quality homes in strong locations are not being created quickly enough to satisfy every buyer looking for them.
Planning constraints, land availability, construction costs and the time required to bring developments to market all limit the speed at which supply can respond.
That does not mean every property will rise in value or that buyers should rush. It does mean that the best homes — correctly priced and in locations with enduring demand — continue to attract attention.
International Buyers Remain a Major Force
Foreign demand continues to be one of Spain’s defining property-market characteristics. The Q1 2026 figures presented in the update show British buyers remaining the largest individual foreign nationality, accounting for roughly 6.8% of foreign purchases. Dutch and Polish buyers also feature strongly, while US demand and interest from Middle Eastern buyers continue to broaden the international profile of the market.
This diversification is significant. The coastal market is no longer dependent on one or two nationalities in the way it may once have been. Buyers now arrive with different motivations: permanent relocation, second-home ownership, lifestyle, retirement, investment, schooling and increasingly flexible working arrangements.
For the Costa del Sol, this international depth is particularly important. It helps explain why demand can remain strong even when one overseas market experiences weaker economic conditions or currency movements.
The Costa del Sol Continues to Command a Premium
The Costa del Sol remains one of the clearest examples of Spain’s prime lifestyle market. Marbella is internationally recognised, but demand now extends well beyond its traditional core. Estepona has continued its transformation, while areas such as Mijas, Benahavís, Nueva Andalucía and Sotogrande attract buyers looking for different combinations of space, amenities, privacy, golf, beaches, schools and accessibility.
Prime property values reflect that demand. The update compares Marbella’s price per square metre with international cities including Stockholm, London and Miami. While Marbella remains below some of those global prime-city benchmarks, the comparison helps explain why overseas buyers can still perceive value even after several years of price growth.
The important point is that buyers are comparing lifestyle markets globally, not merely comparing one Spanish town with another. A purchaser deciding between southern Spain, Portugal, Dubai, Miami or another international destination is assessing climate, connectivity, taxation, schools, security, property quality and lifestyle together.
Not Every Part of the Market Is Moving at the Same Speed
Headlines about national price growth can hide considerable variation. Spain is not one single property market. Madrid behaves differently from Valencia; Mallorca has different supply constraints from inland Andalucía; and a prime villa in Marbella or Sotogrande is not driven by exactly the same factors as a mainstream apartment in a provincial city.
Even within the Costa del Sol, micro-location matters enormously. Sea views, walkability, orientation, plot quality, proximity to schools or golf, community fees, renovation requirements and the scarcity of comparable properties can create substantial differences in value within a very small area.
For sellers, this means a strong market is not an excuse for unrealistic pricing. Buyers are active, but they are also informed. Properties that enter the market at a credible price tend to generate stronger engagement than homes positioned according to aspiration rather than evidence.
What Does This Mean for Buyers?
For buyers, the first half of 2026 reinforces the value of being prepared. In a market where good stock can be limited, knowing your budget, financing position and preferred locations before the right property appears can make a real difference.
It is equally important not to confuse a rising market with a reason to compromise on due diligence. Legal checks, property condition, community information, planning status and the full cost of purchase remain essential. The objective should be to buy the right property at a defensible price, not simply to buy because prices have been moving upwards.
Buyers should also look beyond the headline asking price. Two properties at the same price can represent very different value once location, condition, running costs and future resale appeal are considered.
What Does It Mean for Sellers?
For owners considering a sale, the current environment remains constructive. International demand, constrained supply and continued interest in Spain’s lifestyle destinations create a strong backdrop. But presentation and pricing remain critical.
The first few weeks of a listing are important. A property launched correctly, with strong photography, accurate information and a price supported by comparable evidence, is more likely to capture serious buyers while it is fresh to the market.
Overpricing can have the opposite effect. Even in a rising market, buyers can see what else is available and will often wait rather than pay a price that cannot be justified.
Outlook for the Second Half of 2026
Looking ahead, the underlying picture remains positive, but it is sensible to expect a market driven by fundamentals rather than easy speculation. Interest rates, economic growth and international confidence will continue to influence activity, while the shortage of quality housing in the most desirable locations should remain an important support for prices.
The Costa del Sol appears particularly well positioned because its demand is international, its lifestyle proposition is established and its best locations have genuine supply constraints. At the same time, buyers are increasingly looking beyond the most famous postcodes, creating opportunities in neighbouring areas where quality, infrastructure and value align.
The first half of 2026 therefore tells a fairly clear story: Spain remains attractive, international demand remains broad, and limited supply continues to shape pricing. For buyers and sellers, however, the national headline is only the starting point. The real decision comes down to the specific location, property and price.
That is where local market knowledge matters most. In a strong but increasingly sophisticated market, the best decisions are made by understanding not simply whether Spain is rising, but exactly where demand is strongest, what buyers are paying for, and which properties genuinely stand out.