A Clear Guide to All the Costs (and No Surprises)
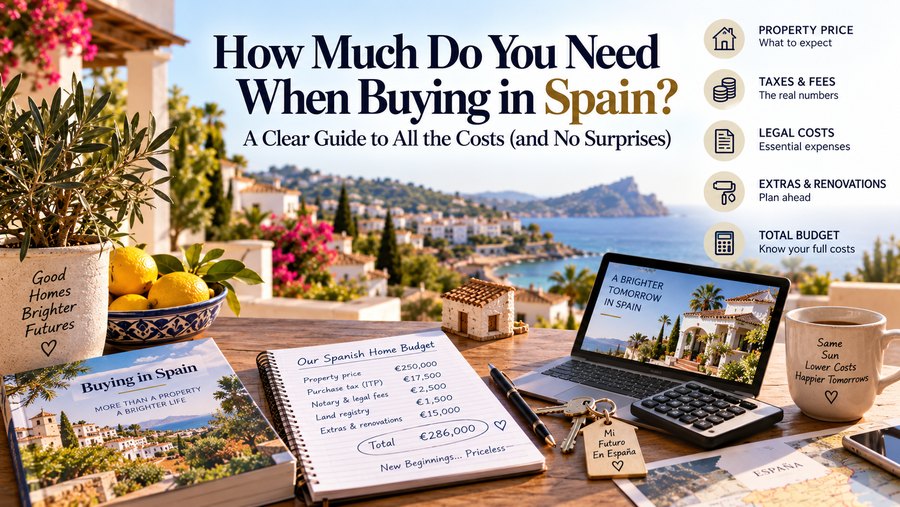
When people start looking at property in Spain, the asking price is naturally the number that gets most of the attention. But the price on the listing is not the full amount you need to complete the purchase. Taxes, professional fees, registration costs and, if you are using finance, the deposit all need to be considered before you decide what you can comfortably afford.
A sensible approach is to work backwards from your total available budget rather than starting with the maximum property price. That gives you room for the costs that sit around the purchase and helps prevent an exciting property search becoming a financial squeeze at completion.
Start with the Purchase Price — Then Add the Buying Costs
There is no single percentage that applies to every property purchase in Spain because taxes vary according to the region and whether you are buying a resale or a new-build property. As a broad planning rule, however, buyers often allow roughly 10% to 15% above the purchase price for taxes and associated acquisition costs.
That does not mean every transaction will cost 15% extra. It means you should establish the actual figures for the property and region before committing yourself.
For example, in Andalucía the general Transfer Tax (ITP) rate on a resale property is currently 7%, although reduced rates can apply in certain qualifying circumstances. Other autonomous communities have their own rates, so a buyer looking in Madrid, Valencia, Cataluña or the Balearics should not assume the Andalucía figure applies to them.
Resale and New-Build Properties Are Taxed Differently
With a resale property, the major purchase tax is normally Transfer Tax. With a new-build purchased from a developer, the tax structure is different and generally involves VAT together with Stamp Duty (AJD), rather than the standard resale-property ITP.
This distinction matters when comparing two homes at a similar asking price. A €500,000 resale and a €500,000 new build do not necessarily require the same amount of cash to complete.
Before making an offer, ask for a purchase-cost estimate based on the specific property. A good estimate should identify the relevant tax treatment instead of simply applying a generic percentage to everything.
Do Not Forget the Professional and Registration Costs
Tax is usually the largest additional expense, but it is not the only one. Buyers should also budget for independent legal advice, notary and Land Registry costs, and any other professional work required for the transaction.
Your lawyer plays an important role in checking the legal position of the property, reviewing documentation and helping ensure that you understand what you are buying before completion. Depending on the property, additional checks or specialist advice may also be appropriate.
These costs are relatively small compared with the purchase price, but they still need to be part of the cash you have available. It is better to include them from day one than discover them after you have already stretched your budget to secure the property.
If You Need a Mortgage, Your Cash Requirement Changes
For a financed purchase, the key question is not simply, “Can I afford the monthly mortgage payment?” It is also, “How much cash do I need before the mortgage begins?”
Spanish lenders do not necessarily finance the entire purchase price, and the amount available can depend on factors such as residency status, income, affordability, the property valuation and the lender's criteria. That means you may need a substantial deposit from your own funds, plus enough cash to cover purchase taxes and costs.
For that reason, buyers using finance should speak to a mortgage adviser or lender early. Knowing your realistic borrowing position before viewing homes gives you a much clearer property budget and avoids building plans around finance that may not be available on the terms you expected.
Keep Money Aside for What Happens After Completion
The budget should not end when you receive the keys. Depending on the home, you may immediately want furniture, decorating, air-conditioning upgrades, landscaping, pool work or renovations.
There are also ongoing ownership costs to consider, such as local property tax, community fees where applicable, insurance, utilities and maintenance. None of these should stop you buying the right property, but they should be visible in your planning.
A useful strategy is to keep a separate contingency fund rather than putting every available euro into the purchase itself. A home feels very different when you can enjoy it from day one without worrying about every unexpected bill.
A Simple Example
Imagine you have €400,000 available in cash for the entire project. It would be risky to search only for properties priced at €400,000 because you would still need to fund the acquisition costs.
Instead, establish the expected taxes and fees first and use what remains to set the maximum purchase price. If you are also planning refurbishment or furnishing, deduct that budget as well.
The exact calculation will vary, but the principle is simple: your property budget and your total buying budget are not the same number.
Know Your Number Before You Start Viewing
Buying in Spain is much easier when the financial side is clear before you fall in love with a property. Work out how much cash you have available, whether you need finance, what taxes apply in the relevant region and how much you want to retain after completion.
Then set your property search around that figure.
The goal is not simply to have enough money to sign at the notary. It is to buy comfortably, understand the real costs and still have the financial breathing room to enjoy the reason you bought in Spain in the first place.